A yield curve is a line plotting the yields of bonds with the same credit quality (usually US Treasuries) against their time to maturity, from 3-month bills to 30-year bonds. A normal curve slopes upward (longer maturities pay more), a flat curve shows similar yields across maturities, and an inverted curve (short-term yields above long-term) has preceded US recessions. Traders use its shape for strategies such as riding the yield curve, and central banks can target it directly through yield curve control. In Excel, MarketXLS returns Treasury yields with functions such as =TreasuryRate3m(), =TreasuryRate1y(), and =TreasuryRate10y(), so you can plot the curve and track the 10-year minus 3-month spread.
Try it in your own spreadsheet
Get the free MarketXLS sample workbook (.xlsx).
No account needed. MarketXLS live data requires a paid plan. Preview workbook
Explore more videos
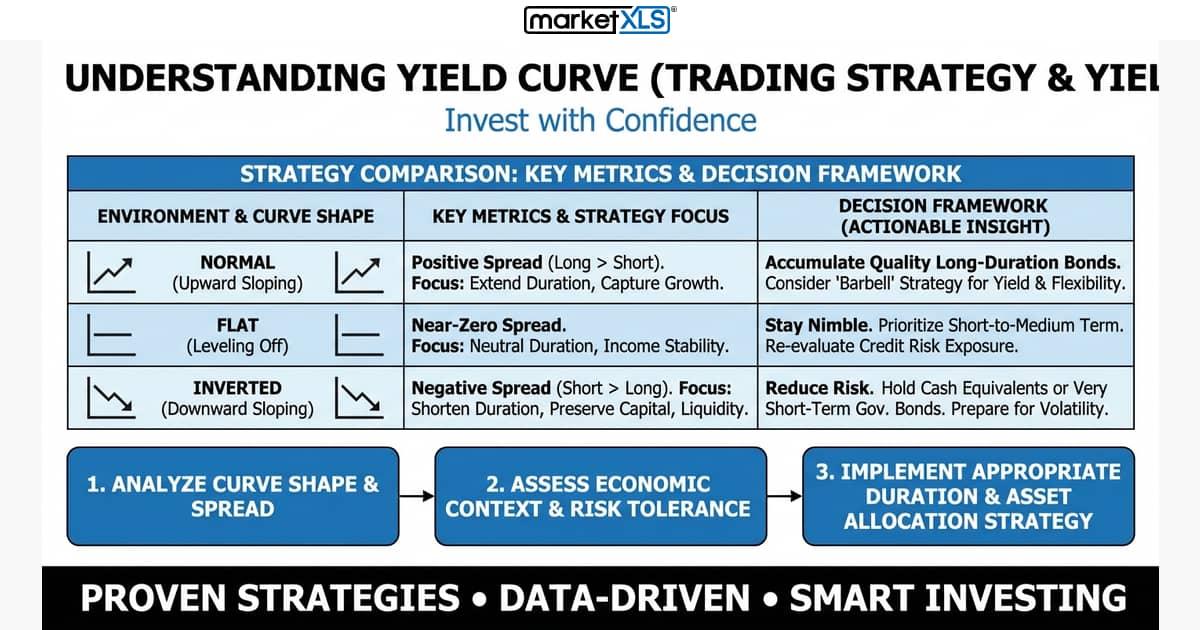
Yield to maturity (YTM) is the effective rate of return that fixed-income securities earn if held to maturity. It depends on the price and coupon rate of the securities. A yield curve is formed by plotting the YTM of bills, notes, and bonds across different maturities. It can be built for:
-
Treasury Instruments
-
Specified Credit Rating Corporate Bond
However, it is important to note that the yield curve is different from the term structure (spot rates), which is calculated using the bootstrapping method (discussion for some time later).
The shape of a yield curve can be of three types:
-
Positively sloped (Normal)- Normally, yield curves are positively sloped where the yield for shorter maturity is less than that for longer maturities. The premium on longer maturities exists due to larger uncertainty over the longer time period, which is termed as Liquidity Premium Theory. This is when people expect the short-term interest rates to rise over the period.
-
Flat – The fed rates largely influence the shorter maturity side of the graph. So, if the Federal Reserve increases the short-term rates or the buy traffic in the longer-term maturities increases, the slope of the curve reduces. This phenomenon is called flattening of the curve.
-
Negative Sloped (Inverted)- Further push on short-term rates by the Federal Reserve and higher traffic on long-term maturity leads to a negative slope which is called an inverted yield curve
A prolonged inversion of the treasury yield curve for months has been argued to be a leading indicator of upcoming recession within the next 1-1.5 years in the US market for the last 50 years. The spread between 3-month and 10-year Treasury yields can be used to track these inversions.
The movement in the yield curve can be of 3 different natures:
-
Level (Parallel Shift) – When there is an almost equal increase/decrease in the yield across various maturity periods, the yield curve shifts parallelly.
-
Slope (Steepening or Flattening) – When there is an unequal change in the yield curve across maturity periods.
-
Curvature- When the short-term & long-term yields change with a greater magnitude than that of the mid-term.
The curvature of a yield curve is measured by butterfly spread.
Butterfly Spread = 2 × Medium (10 yr) Term Yield − Short (2 yr) Term Yield − Long (30 yr) Term Yield
Riding the yield curve strategy
Riding the yield curve means buying a longer bond than your holding period and selling it early, to earn more than a bond that matches your horizon. The strategy assumes the yield curve is upward sloping and stays unchanged. Suppose 3-year bonds yield 4.4%, 7-year bonds yield 4.9%, and 10-year bonds yield 5.5%, and an investor needs to invest for 3 years. Instead of buying a 3-year bond, the investor buys a 10-year bond.
So, after 3 years, the remaining maturity of the bond will be 7 years, and the yield will be at 4.9%, i.e., lesser than 5.5%. As we know, rates of interest and bond prices are inversely related, there will be capital appreciation in the price of the 10-year bond, and thus the investor will earn more than the initial 4.4% in case of buying a 3-year bond.
However, the downside to this strategy is that by buying 10 yr bond instead of 3yr bond, the duration of the portfolio increases, which makes it more sensitive to interest rate changes.
Yield curve control
When the bond yields are set by the central bank in the form of an unconventional monetary policy, it is called Yield Curve Control. The central bank targets an interest rate at a specific maturity by buying the necessary quantity of debt and pegs the yield at the decided level. It is different from quantitative easing, where the target is not a specific interest rate but a specific quantity of bonds.
In 2016, the Bank of Japan pegged the yield of the 10-year Japanese Government Bonds at 0% with a fluctuation band of 10 basis points. The band was widened to 20 basis points in 2018.
The bottom line
As of December 2020, the outstanding value of fixed income instruments issued by the government and private bodies in the United States was about $50 trillion, and more than $800 billion of new instruments had been issued each month over the prior 12 months. The yield curve summarizes how that market prices time and risk, and it is widely used to infer the direction of the economy.
Disclaimer
All trademarks referenced are the property of their respective owners. Other trademarks and trade names may be used in this document to refer to either the entity claiming the marks and names or their products. MarketXLS disclaims any proprietary interest in trademarks and trade names other than its own, or affiliation with the trademark owners.
None of the content published on marketxls.com constitutes a recommendation that any particular security, portfolio of securities, transaction, or investment strategy is suitable for any specific person. The author is not offering any professional advice of any kind. The reader should consult a professional financial advisor to determine their suitability for any strategies discussed herein. The article is written for helping users collect the required information from various sources deemed to be an authority in their content. The trademarks if any are the property of their owners and no representations are made.