
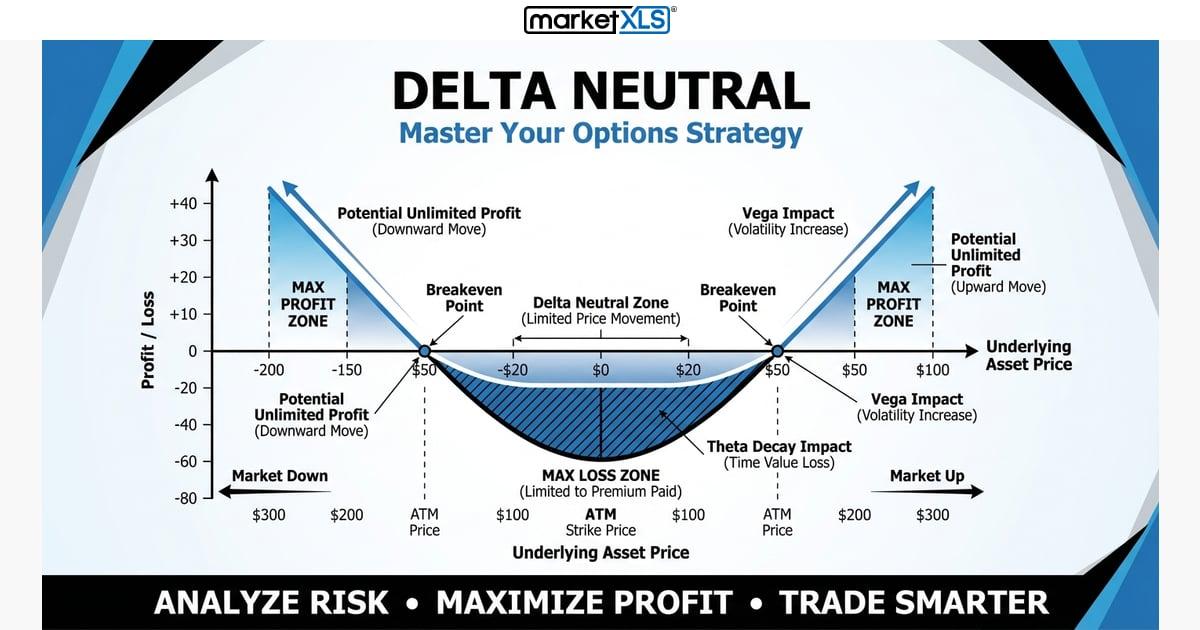
A delta neutral position is an options position whose total delta is close to zero, so small moves in the underlying stock barely change its value. Traders use delta neutral positions to profit from time decay or changes in implied volatility instead of from price direction, or to hedge a stock position for a short period. For a quick overview of the Greeks, see this guide to option premium.
Why traders use delta neutral positions
Delta neutral traders want no directional risk. Instead of betting on whether the stock goes up or down, they profit from other factors that affect option prices, such as time decay and changes in implied volatility. If you have ever entered a trade with conviction only to see the market move the other way right after, a delta neutral position removes that price-direction bet.
How to profit from a delta neutral position
In delta neutral trading you keep the position's delta near 0, so profit comes from the other inputs to option prices:
- Time decay. A delta neutral position is not affected by small moves in the stock, but the option premiums still decay. A short straddle, for example, profits if the stock stays roughly where it is.
- Volatility. A delta neutral position can profit from a change in implied volatility without a large directional bet. This is useful when implied volatility is expected to change soon.
- Large moves (long gamma). A long straddle is delta neutral at entry but gamma positive. Gamma increases the position's delta in the direction of a large move, so the position can profit if the stock moves sharply either way.
Delta neutral hedging
Delta neutral hedging protects a stock position from short-term price swings while you keep the shares. It is used during periods of uncertainty, such as when a stock is near support or resistance.
Example. You own 100 shares of a stock trading at $200. You expect the price to rise over the long run but may fall in the short run. The shares give you a delta of +100 (100 shares x 1.0). To bring the total to zero you need -100 delta. One way is to buy 2 at-the-money put contracts. Each contract covers 100 shares and has a delta of about -0.5 per share, or -50 per contract.
Overall delta = (100 x 1) + (2 contracts x 100 x -0.5) = 0
Delta changes as the stock moves and time passes, so the hedge must be rebalanced to stay neutral.
Short call or long put for the hedge
You can reach delta neutral with either short calls or long puts, since both have negative delta. Short calls collect premium, so time decay works in your favor, but they provide only limited downside protection (the premium received). Long puts protect against losses below the strike price, but you pay the premium and time decay works against you.
Tracking delta in Excel with MarketXLS
- Use the MarketXLS
=opt_Delta(CurrentStockPrice, MarketOptionPrice, ExpiryDate, OptionType, StrikePrice)function to calculate an option's delta in Excel, then sum position deltas to check that you are near zero.
Disclaimer
None of the content published on marketxls.com constitutes a recommendation that any particular security, portfolio of securities, transaction, or investment strategy is suitable for any specific person. The author is not offering any professional advice of any kind. The reader should consult a professional financial advisor to determine their suitability for any strategies discussed herein.
