
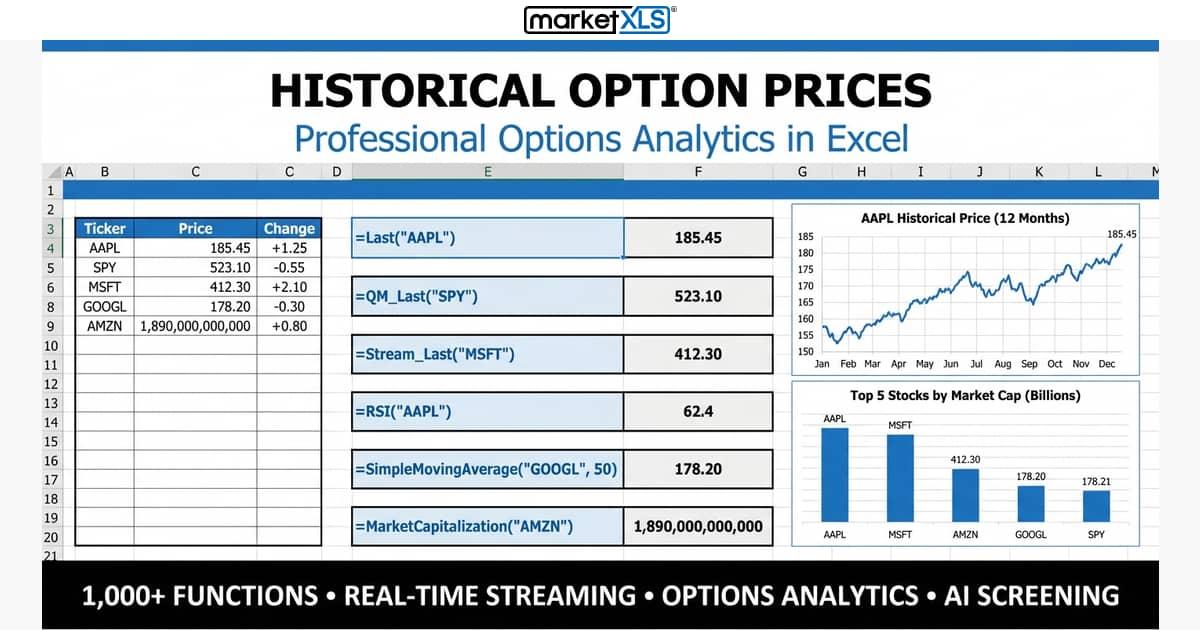
Historical option prices are past quotes for option contracts, and you can pull them into Excel with MarketXLS in three ways. =OPT_HistoricalOptionChain("AAPL",DATE(2026,8,14)) returns the whole chain as it stood on one past date, =Bid_Historical(A2,DATE(2026,8,14)) (or Ask_Historical) returns one contract's past bid or ask when A2 holds the option symbol, and =OPT_DeltaHistorical(A2,DATE(2026,8,14)) and the other OPT_*Historical functions return a contract's past Greeks. Traders use this data to backtest strategies such as covered calls and put spreads, to study implied volatility around earnings, and to check whether current premiums are rich or cheap. This guide covers the formulas, what the data contains, and practical ways to use it.
Why Historical Option Prices Matter
Backtesting Trading Strategies
The most common use of historical option prices is strategy backtesting. Before risking real capital on an options strategy, you want to know how it would have performed in the past under different market conditions.
For example, if you want to sell weekly put options on a stock, historical data lets you examine:
- What premium was available at various strike prices over the past year
- How often the options expired in the money (resulting in assignment)
- What the total profit or loss would have been across all trades
- How the strategy performed during high-volatility periods versus calm markets
Without historical option prices, strategy backtesting is impossible. You would be forced to forward-test with real money, which is both risky and slow.
Implied Volatility Analysis
Historical option prices allow you to reconstruct historical implied volatility (IV) levels. Since option prices embed the market's expectation of future volatility, tracking how IV changes over time reveals critical trading patterns:
- IV rank: Where current IV sits relative to its historical range (e.g., "IV is at the 85th percentile of its 52-week range")
- IV around events: How implied volatility typically behaves before and after earnings announcements, FDA decisions, or economic releases
- Volatility mean reversion: IV tends to revert to its historical average, creating trading opportunities when it is unusually high or low
- Term structure dynamics: How the IV curve across different expiration dates changes over time
Premium Decay Analysis
Options lose value as they approach expiration due to time decay (theta). Historical data lets you study:
- The rate of premium decay for different types of options
- Whether certain days of the week or times of the month show faster decay
- How decay interacts with underlying price movements
Risk Management
Historical option prices help you calibrate risk management parameters:
- What is the maximum drawdown a particular strategy experienced?
- How wide do option spreads need to be to avoid excessive losses?
- What delta range provides the best risk-reward balance historically?
How to Access Historical Option Prices in Excel
MarketXLS provides separate functions for a past option chain, one contract's past price, and one contract's past Greeks. In the Microsoft 365 add-in (Excel for Mac and Excel for the web), add the mxls. prefix to each function, for example =mxls.OPT_HistoricalOptionChain("AAPL",DATE(2026,8,14)).
Getting a historical option chain and one contract's past prices
| Task | Windows desktop formula |
|---|---|
| Chain on one past date | =OPT_HistoricalOptionChain("AAPL",DATE(2026,8,14)) |
| One contract's past bid | =Bid_Historical(A2,DATE(2026,8,14)) |
| One contract's past ask | =Ask_Historical(A2,DATE(2026,8,14)) |
| One contract's past delta | =OPT_DeltaHistorical(A2,DATE(2026,8,14)) |
| Other past Greeks and IV | OPT_GammaHistorical, OPT_ThetaHistorical, OPT_VegaHistorical, OPT_RhoHistorical, OPT_ImpliedVolatilityHistorical |
Cell A2 holds the exact option symbol, built with =OptionSymbol("AAPL",DATE(2026,9,18),"C",250) or copied from a returned chain. Use a real Excel date (for example DATE(2026,8,14)) rather than a date typed as text. A weekend, market holiday, or a date before the contract was listed returns NA. See the options data guide for details.
Getting Historical Option Prices with QM_GetHistory
The =QM_GetHistory() function retrieves end-of-day historical prices for any option contract. To use it, you need the option symbol in the standard format:
=QM_GetHistory("@AAPL 250321C00200000")
Formula documentation: QM_GetHistory
This returns the historical price data for the AAPL March 21, 2025, $200 call option.
The option symbol format is: @TICKER YYMMDD[C/P]SSSSSSSSS
@prefix identifies it as an optionTICKERis the underlying stock symbolYYMMDDis the expiration dateCfor call,Pfor put- The final 8 digits are the strike price multiplied by 1,000 (for example,
00200000for a $200 strike)
Getting Historical Prices with GetHistory
You can also use =GetHistory() with date range parameters:
=GetHistory("@AAPL 250321C00200000", "2024-06-01", "2025-03-01", "Daily")
Formula documentation: GetHistory
This returns daily historical prices between the specified dates.
Getting Current Option Chains
To see all available options for a stock at current prices, use:
=QM_GetOptionChain("AAPL")
Formula documentation: QM_GetOptionChain
This returns the complete option chain including all available expirations and strike prices with current bid, ask, volume, open interest, and Greeks.
For S&P 500 index options:
=QM_GetOptionChain("^SPX")
Formula documentation: QM_GetOptionChain
Building Option Symbols
Use =OptionSymbol() to construct option symbols programmatically:
=OptionSymbol("AAPL", "2025-06-20", "C", 200)
Formula documentation: OptionSymbol
This returns @AAPL 250620C00200000, which you can then pass to =QM_Last() for current prices or =QM_GetHistory() for historical prices.
Getting Current Option Prices
For a current option quote:
=QM_Last("@AAPL 250620C00200000")
Formula documentation: QM_Last
QM_Last returns the last traded price as an on-demand snapshot that updates when Excel recalculates. For ticking prices, use =QM_Stream_Last() with streaming on. Options data is end-of-day on the Standard plan and real-time on the Advanced and Business plans.
Getting Option Greeks and Detailed Quotes
For comprehensive option data including all Greeks:
=QM_GetOptionQuotesAndGreeks("AAPL")
Formula documentation: QM_GetOptionQuotesAndGreeks
This returns bid, ask, last price, volume, open interest, delta, gamma, theta, vega, rho, and implied volatility for all available contracts.
Historical Option Price Data: What Is Included
When you retrieve historical option prices, the data typically includes:
| Data Field | Description | Use Case |
|---|---|---|
| Date | Trading date | Time series analysis |
| Open | Opening price | Gap analysis |
| High | Highest price of the day | Intraday range analysis |
| Low | Lowest price of the day | Support/resistance levels |
| Close | Closing/settlement price | Strategy backtesting |
| Volume | Number of contracts traded | Liquidity analysis |
| Open Interest | Total outstanding contracts | Market sentiment, positioning |
Understanding Option Price Components
Historical option prices reflect several factors at the time of the trade:
- Intrinsic value: The amount the option is in the money (strike vs. stock price)
- Time value (extrinsic value): The premium above intrinsic value, driven by time to expiration and implied volatility
- Implied volatility: The market's expectation of future price movement embedded in the option price
- Interest rates: The cost of carry component
- Dividends: Expected dividend payments between now and expiration
When analyzing historical prices, it is important to consider what was driving the price at each point in time. A high option price might reflect high implied volatility rather than the option being deep in the money.
Practical Applications of Historical Option Data
Application 1: Covered Call Backtesting
Covered call writing is one of the most popular options strategies. Historical data lets you evaluate:
Step 1: Pull historical stock prices:
=GetHistory("AAPL", "2023-01-01", "2025-01-01", "Daily")
Formula documentation: GetHistory
Step 2: For each month, find the option that was approximately 5% out of the money:
=OptionSymbol("AAPL", "2024-02-16", "C", 195)
Formula documentation: OptionSymbol
Step 3: Get the historical premium received:
=QM_GetHistory("@AAPL 240216C00195000")
Formula documentation: QM_GetHistory
Step 4: Track outcomes — did the option expire worthless (keep premium), or was the stock called away? Calculate total return including premium received and any capital gains or losses.
By repeating this analysis across many months, you can determine:
- Average monthly premium collected as a percentage of the stock price
- Win rate (percentage of months the option expired worthless)
- Total return versus simply holding the stock
- Performance during high-volatility versus low-volatility periods
Application 2: Implied Volatility Study Around Earnings
Earnings announcements are among the most predictable volatility events. Historical option prices reveal consistent patterns:
Step 1: Identify earnings dates for the past two years
Step 2: Pull option prices for the at-the-money straddle 30 days before, 7 days before, and 1 day before each earnings date:
=QM_GetHistory("@AAPL 240726C00220000")
Formula documentation: QM_GetHistory
Step 3: Calculate the implied volatility from these prices using a pricing model
Step 4: Analyze patterns:
- IV typically rises steadily into earnings (the "IV ramp")
- IV drops sharply after the announcement (the "IV crush")
- The magnitude of the IV crush varies by stock and quarter
- Understanding these patterns helps you time volatility trades
Application 3: Put Spread Risk Analysis
Vertical put spreads are popular defined-risk strategies. Historical data helps you calibrate spread width and strike selection:
Step 1: Pull historical data for puts at various strike prices:
=QM_GetHistory("@SPY 241220P00550000")
=QM_GetHistory("@SPY 241220P00540000")
Formula documentation: QM_GetHistory
Step 2: Calculate the historical spread value at entry and at expiration
Step 3: Determine the probability of profit based on how often the underlying remained above the short strike
Step 4: Optimize strike selection based on historical win rates and average profit/loss
Application 4: Volatility Skew Analysis
Volatility skew refers to the pattern where out-of-the-money puts typically have higher implied volatility than out-of-the-money calls. Historical data lets you:
- Track how skew changes over time
- Identify periods of extreme skew (potential trading opportunities)
- Compare current skew to historical averages
- Analyze skew behavior before and after major market events
Historical Option Data Methods Comparison
Different approaches to obtaining and using historical option data:
| Method | Coverage | Cost | Data Quality | Best For |
|---|---|---|---|---|
| MarketXLS Excel Functions | US-listed options | Subscription-based | Varies by contract and date | Excel-based analysis and backtesting |
| CBOE DataShop | CBOE-listed options | Per-dataset pricing | Institutional grade | Academic research, comprehensive studies |
| Options Clearing Corp (OCC) | All US-listed options | Variable | High | Regulatory and compliance analysis |
| Broker Platforms | Limited history | Included with account | Varies | Quick lookups, recent history |
| Free Online Sources | Very limited | Free | Low reliability | Basic research only |
The practical difference with MarketXLS is that the data lands in Excel cells, so you can apply formulas and charts without a separate import or formatting step.
Building an Options Analysis Spreadsheet
Basic Options Tracker
Create a spreadsheet that tracks your options positions with real-time data:
Column A: Option Symbol (built with =OptionSymbol())
=OptionSymbol("AAPL", "2025-06-20", "C", 200)
=OptionSymbol("MSFT", "2025-06-20", "P", 400)
=OptionSymbol("AMZN", "2025-07-18", "C", 200)
Formula documentation: OptionSymbol
Column B: Current Price
=QM_Last("@AAPL 250620C00200000")
=QM_Last("@MSFT 250620P00400000")
=QM_Last("@AMZN 250718C00200000")
Formula documentation: QM_Last
Column C: Entry Price (manually entered)
Column D: P&L per contract
= (B2 - C2) × 100
Column E: Underlying Current Price
=Last("AAPL")
=Last("MSFT")
=Last("AMZN")
Formula documentation: Last
Greeks Dashboard
Build a dashboard that shows real-time Greeks for all positions:
=QM_GetOptionQuotesAndGreeks("AAPL")
Formula documentation: QM_GetOptionQuotesAndGreeks
This returns comprehensive data including delta, gamma, theta, vega, and implied volatility for every available AAPL option contract. Use this to:
- Monitor your portfolio's net delta (directional exposure)
- Track theta (daily time decay in your favor or against you)
- Watch vega (sensitivity to implied volatility changes)
- Manage gamma risk around expiration
Historical Comparison Tool
Create a tool that compares current option prices to historical averages:
Step 1: Get current at-the-money option price:
=QM_Last("@AAPL 250620C00220000")
Formula documentation: QM_Last
Step 2: Get the same relative option price from past periods:
=QM_GetHistory("@AAPL 240621C00195000")
Formula documentation: QM_GetHistory
Step 3: Calculate whether current premiums are above or below historical averages, indicating whether options are relatively expensive or cheap.
Options Data Quality Considerations
Bid-Ask Spread Impact
Historical option prices typically reflect the last traded price or the settlement price, not the mid-market price. For illiquid options with wide bid-ask spreads, the last traded price may not accurately represent the fair value. When backtesting:
- Use mid-market estimates (average of bid and ask) when possible
- Add realistic slippage to your backtest assumptions
- Focus on liquid options (high volume, tight spreads) for more reliable analysis
Corporate Actions
Stock splits, mergers, special dividends, and spin-offs can create adjusted option contracts with non-standard terms. Historical prices for these adjusted options may look unusual unless you account for the corporate action. Always check whether an option symbol represents a standard or adjusted contract.
Expiration and Exercise
Options that expire worthless have a final value of zero, but this may not always appear in historical data if no trades occurred on the last day. When backtesting, explicitly handle expiration:
- In-the-money options: Assume exercise (or assignment for short positions)
- Out-of-the-money options: Value = 0
- At-the-money options: May or may not be exercised depending on transaction costs
Data Gaps
Some option contracts, especially far out-of-the-money or far-dated options, may have days with no trading activity. This results in gaps in the historical data. For backtesting, you can either skip these days or interpolate using a pricing model.
Advanced Historical Options Analysis
Volatility Surface Construction
Using historical option prices across multiple strikes and expirations, you can construct a volatility surface — a three-dimensional representation of implied volatility as a function of strike price and time to expiration.
Pull prices for options at multiple strikes:
=QM_Last("@AAPL 250620C00190000")
=QM_Last("@AAPL 250620C00200000")
=QM_Last("@AAPL 250620C00210000")
=QM_Last("@AAPL 250620C00220000")
=QM_Last("@AAPL 250620C00230000")
Formula documentation: QM_Last
Calculate implied volatility from each price using a pricing model, then plot the surface to visualize:
- Skew: How IV varies across strikes at a single expiration
- Term structure: How IV varies across expirations at a single strike
- Surface dynamics: How the entire surface shifts over time
Put-Call Parity Verification
Put-call parity states that for European options: Call Price - Put Price = Stock Price - Strike Price × e^(-rT)
Using historical data, you can verify that this relationship held. Significant deviations from put-call parity may indicate:
- Market stress or dislocation
- Dividend expectation changes
- Borrowing cost spikes
- Arbitrage opportunities (historically)
Term Structure Analysis
The implied volatility term structure shows how IV varies across different expiration dates. Historical analysis reveals:
- How term structure flattens or inverts during market stress
- Seasonal patterns (e.g., IV tends to be higher for expirations spanning earnings dates)
- The relationship between short-term and long-term IV expectations
Pull options at different expirations:
=QM_GetOptionChain("AAPL")
Formula documentation: QM_GetOptionChain
This returns all available expirations, allowing you to construct and analyze the term structure.
Common Mistakes When Using Historical Option Data
Mistake 1: Survivorship Bias
Only analyzing options on stocks that still exist today creates survivorship bias. Companies that went bankrupt or were acquired are missing from the dataset, potentially making strategies look better than they actually were.
Mistake 2: Ignoring Transaction Costs
Options trading involves commissions, bid-ask spread costs, and potential assignment fees. A strategy that shows small profits in backtesting may be unprofitable after accounting for these real-world costs. Always include realistic transaction cost estimates.
Mistake 3: Overfitting
Optimizing strategy parameters to perfectly fit historical data often produces strategies that fail in live trading. Use out-of-sample testing: optimize on one time period and validate on a different, unseen period.
Mistake 4: Assuming Constant Liquidity
Liquidity conditions change over time. An option that was liquid in the past may not be liquid today, and vice versa. Historical volume and open interest data help assess whether past trading conditions are representative.
Mistake 5: Ignoring Early Exercise Risk
American-style options (most individual stock options) can be exercised early. This risk is not captured by simply looking at historical prices at expiration. Deep in-the-money options, especially puts near ex-dividend dates, have meaningful early exercise risk that must be factored into analysis.
Frequently Asked Questions
Where can I find historical option prices?
In Excel, the MarketXLS add-in returns a past option chain with =OPT_HistoricalOptionChain("AAPL",DATE(2026,8,14)) and one contract's past bid or ask with =Bid_Historical or =Ask_Historical. Outside Excel, Cboe DataShop sells historical datasets for research, and broker platforms such as thinkorswim and Interactive Brokers show limited option history inside their own software.
How do I read an option symbol?
Option symbols follow the format @TICKER YYMMDD[C/P]SSSSSSSSS. The @ prefix identifies it as an option. The ticker is the underlying stock symbol. YYMMDD is the expiration date (year, month, day). C indicates a call and P indicates a put. The final digits represent the strike price multiplied by 1,000. For example, @AAPL 250620C00200000 is an AAPL call option expiring June 20, 2025, with a $200 strike price. You can build symbols automatically using =OptionSymbol("AAPL", "2025-06-20", "C", 200).
Can I backtest options strategies with historical prices?
Yes, historical option prices are the foundation of options strategy backtesting. Use =QM_GetHistory() or =GetHistory() to retrieve past prices for specific option contracts. Combine this with historical stock prices from =GetHistory("AAPL", "2023-01-01", "2025-01-01", "Daily") to reconstruct the complete picture of how a strategy would have performed. Track entry prices, exit prices, premium collected or paid, and assignment outcomes to calculate historical profit and loss.
What is implied volatility and how does historical data help?
Implied volatility (IV) is the market's expectation of future price movement, embedded in option prices. Historical option data lets you calculate what IV was at any point in the past, revealing patterns like the "IV ramp" before earnings and the "IV crush" afterward. By comparing current IV to its historical range, you can determine whether options are relatively expensive or cheap. This comparison, known as IV rank or IV percentile, requires historical option price or implied volatility data.
How far back does historical option data go?
The availability of historical option data depends on the data provider and the specific option contract. A historical request for a date before the contract was listed returns NA, so check that the contract existed on your date. Keep in mind that option contracts have limited lifespans: they expire and cease to exist. To analyze long time periods, you need to chain together data from successive option contracts (e.g., monthly at-the-money calls over a two-year period).
How do I handle option data around stock splits?
Stock splits create adjusted option contracts with non-standard terms. For example, a 2-for-1 split would double the number of contracts and halve the strike price for existing options. Historical prices before and after the split may appear discontinuous if you do not account for the adjustment. When backtesting across stock splits, use adjusted prices or limit your analysis to periods without splits. Check the Options Clearing Corporation (OCC) for details on how specific corporate actions affected option contract terms.
Getting Started with Historical Options Analysis
With MarketXLS you can pull historical options data into Excel and analyze it with ordinary formulas.
Here is your workflow:
- Build option symbols: Use
=OptionSymbol("AAPL",DATE(2025,6,20),"C",200)to construct symbols programmatically - Pull historical data: Use
=OPT_HistoricalOptionChain()for a past chain,=Bid_Historical()or=Ask_Historical()for one contract, andOPT_*Historicalfunctions for past Greeks - Analyze current chains: Use
=QM_GetOptionChain("AAPL")to see all available contracts - Get current prices: Use
=QM_Last()for current option quotes (real-time on Advanced and Business, end-of-day on Standard) - Study Greeks: Use
=QM_GetOptionQuotesAndGreeks("AAPL")for comprehensive option analytics
Visit MarketXLS to start analyzing historical option prices in Excel. Check the pricing page for subscription options that include options data access.
None of the content published on marketxls.com constitutes a recommendation that any particular security, portfolio of securities, transaction, or investment strategy is suitable for any specific person. The author is not offering any professional advice of any kind. The reader should consult a professional financial advisor to determine their suitability for any strategies discussed herein. The article is written to help users collect the required information from various sources deemed to be an authority in their content.
